How to Build Your First Emergency Fund in Your 20s
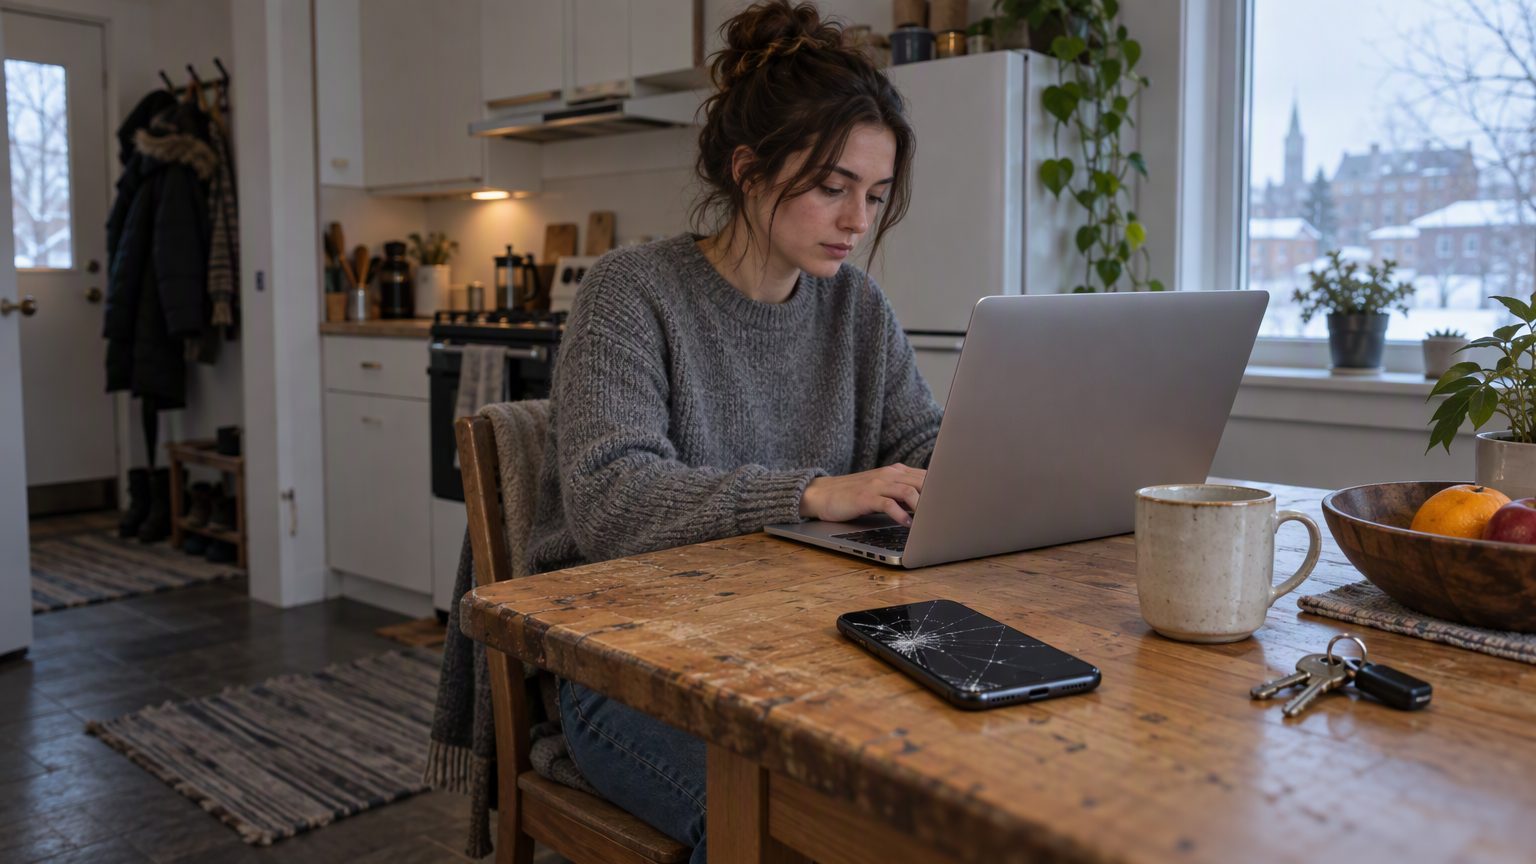
Your work phone cracks on a Tuesday, rent comes out Friday, and payday is still nine days away. An emergency fund exists to bridge exactly that kind of gap, with cash on hand for expenses that are both necessary and unexpected. Park it in its own high-interest savings account, well away from bill money and vacation savings, so one bad week doesn't snowball into an overdraft spiral.
Building the fund isn't complicated. Start with a small first target, keep the money in a separate spot, and set up an automatic transfer for every payday. The accounts below are a starting point for comparison, not a ranking.
| Name | Potential advantages | Potential limitations | Cost structure |
|---|---|---|---|
| KOHO High Interest Savings | Automated savings tools | Interest opt-in required | Plan-dependent |
| EQ Bank Personal Account | Everyday banking access | Digital-only service | No monthly fee |
| Wealthsimple Cash Account | Paycheque allocation | Digital account management | No monthly fee |
| Tangerine Savings Account | Named savings goals | Promotions expire | Check fee schedule |
| Simplii High Interest Savings Account | Recurring deposits | Unavailable in Quebec | No monthly fee |
| Oaken Savings Account | Dedicated savings | No debit card | No monthly fee |
| Saven High Interest Savings Account | Small starting balances | Provincial restrictions | No monthly fee |
| Scotia High Interest Savings Account | Internal transfers | Relationship balance requirement | No monthly fee; withdrawal charges may apply |
| Canadian Tire Bank High Interest Savings Account | Flat-rate structure | External transfers required | No monthly fee |
Rates and terms change. Before you open anything, look at the fees, the eligibility rules, and how long a withdrawal takes to reach you. Sometimes a headline rate only shows up if you're on a paid plan or have a qualifying direct deposit.
Know what counts as an emergency
An emergency is urgent, it's necessary, and you couldn't reasonably have predicted it. A sudden layoff counts. So does uninsured dental work. Your annual insurance renewal? No, because you knew it was coming.
Could you put the expense on next month's calendar? Then it belongs in a separate sinking fund, saved for on its own. A car repair is borderline. If you need the vehicle for work and there's no bus route to fall back on, it counts.
Set a first target that fits your income
A first target of $500, or one essential bill, is perfectly legitimate. Build it through small regular deposits without missing rent or minimum debt payments, even when entry-level wages leave almost nothing to spare.
For the next milestone, add up what you truly can't skip: housing, basic groceries, required transportation, insurance, utilities, and medication. Required student loan payments go in that pile. Optional subscriptions and accelerated debt repayments don't. Say the total comes to $2,000 a month. Your next stop is one month of costs, and eventually three, which works out to $6,000.
Choose a high-interest savings account
Where should the fund live? Somewhere separate, low-fee, and boring. It should earn interest, let you pull money out reasonably fast, and never touch the stock market. Compare ongoing rates rather than welcome offers, since the promo rate expires and the regular one is what you actually keep.
KOHO High Interest Savings
KOHO combines prepaid Mastercard spending with automated Goal Savings and purchase rounding, which banks the difference on every purchase. Its High Interest Savings Account pays up to 3.5% interest on eligible balances, and the rate depends on the plan you choose. One catch: you have to opt into Earn Interest in the app before any of it accrues.
| Access and savings | Money remains accessible; earmark your reserve in Goal Savings. |
|---|---|
| Interest calculation | Calculated daily and paid monthly. |
| Cost and minimum | No minimum balance; plan costs vary. |
| Emergency fund checks | Confirm plan terms and how funds are held and protected. |
EQ Bank Personal Account
This digital hybrid combines everyday banking with savings interest. Keep your reserve in a separate internal account so it stays out of sight.
| Access and automation | Transfers, card access, and direct deposit. |
|---|---|
| Cost and minimum | No monthly fee or minimum balance. |
| Emergency fund checks | Convenient access; check conditional rates and qualifying deposit requirements. |
Wealthsimple Cash Account
Automatic paycheque allocation suits existing Wealthsimple users. Keep emergency cash out of stocks and cryptocurrency.
| Access model | Digital spending account with card access and transfers. |
|---|---|
| Cost structure | No monthly account fee; check service-specific charges. |
| Emergency fund checks | Confirm the current Cash or chequing product name and deposit protection arrangement. |
Tangerine Savings Account
Savings Goals and the Automatic Savings Program let you name your reserve and schedule contributions. Label yours "Emergency Fund" and leave it alone.
| Access model | Online savings with transfers to linked accounts. |
|---|---|
| Cost structure | Check savings account and transaction fees. |
| Emergency fund checks | Compare regular rates with promotional expiry dates; confirm transfer timing. |
Simplii High Interest Savings Account
Recurring deposits help you build a separate reserve. Welcome rates eventually revert to variable, tiered regular rates.
| Access model | Digital savings with withdrawals through linked accounts. |
|---|---|
| Cost and minimum | No monthly fee or minimum balance. |
| Emergency fund checks | Unavailable in Quebec; check transfer timing and promotion eligibility. |
Oaken Savings Account
Oaken separates savings from everyday purchases, but you'll need a linked account for urgent bills.
| Access and automation | External transfers and automatic contributions; no card or ATM access. |
|---|---|
| Cost and minimum | No monthly fee or minimum balance. |
| Emergency fund checks | Confirm transfer timing and issuing institution. |
Saven High Interest Savings Account
Check provincial eligibility before applying.
| Access and interest | Online access; interest calculated daily and paid monthly. |
|---|---|
| Cost and minimum | No monthly fee or minimum deposit. |
| Emergency fund checks | Unavailable in Quebec; confirm transfer timing and provincial deposit protection. |
Scotia High Interest Savings Account
Relationship-based interest depends on eligible balances across Scotiabank, which can make this account a poor fit for a small starter fund.
| Access and automation | Internal transfers; confirm recurring transfer options. |
|---|---|
| Cost structure | No monthly fee; withdrawal charges may apply. |
| Emergency fund checks | Verify the qualifying relationship balance and ongoing rate. |
Canadian Tire Bank High Interest Savings Account
This savings-only account pays a flat variable rate. External transfers add separation but may delay access when you need cash fast.
| Access and automation | No card, ATM access, or e-Transfers. Confirm recurring deposit support. |
|---|---|
| Cost and minimum | No monthly fee or minimum balance. |
| Emergency fund checks | Unavailable in Quebec; check transfer limits and timing. |
How to compare the options
Access beats a flashy rate. A spending hybrid gets you card access on the spot; savings-only accounts make you transfer first. Test a small withdrawal before you rely on any external transfer.
Check which deposits and categories CDIC covers, and don't assume every account above carries the same protection. For fintech accounts, review how funds are held with member institutions. For credit unions, look up the provincial protection scheme.
Automate a small payday transfer
Set the transfer for the day your paycheck lands, at an amount that won't force a missed bill or an overdraft. Twenty dollars every two weeks becomes $520 over 26 pay periods before interest. Start below your maximum. If a month goes by without borrowing to cover bills, bump it up. With irregular income, automate a small base you can always cover, then add a slice of the bigger cheques.
Find money without cutting everything fun
- Redirect a cancelled subscription's monthly cost.
- Save part of a tax refund or cash-back payout.
- Transfer the difference after negotiating a phone or insurance bill.
- Move leftover grocery or entertainment money before payday.
You don't have to cancel every social plan, and a tight budget doesn't mean you've been irresponsible. If there's genuinely nothing to cut, a gift or an extra paid shift can start the buffer instead.
Use the fund and rebuild it
Using it isn't a failure. That's what it's for. After a real emergency, restart your contributions and rebuild the previous milestone before raising your target.
If the emergency added a recurring expense, recalculate your essentials. And once you hit the later milestone, reassess: job security, health needs, dependants, and family support all change how big the fund needs to be.
Start with the next payday
Pick your first milestone and schedule a transfer you can live with before the next payday. Small deposits count, even before the fund is fully built.