Why Insurance Companies Delay, Dispute, and Undervalue Accident Injury Claims
A collision takes seconds, but the claim that follows can stretch on for months. In that time, the person who was hurt is usually dealing with pain, missed work, and a stack of bills that keeps growing, while the company on the other side of the claim is under no similar pressure.
That imbalance is not accidental. Anyone filing a claim after a crash in Tampa, FL, quickly learns that an adjuster's job is not to pay what a case is worth, but to close the file for as little as the company can reasonably get away with. Understanding how that happens makes it far easier to protect yourself.
The Pressure That Builds After a Crash
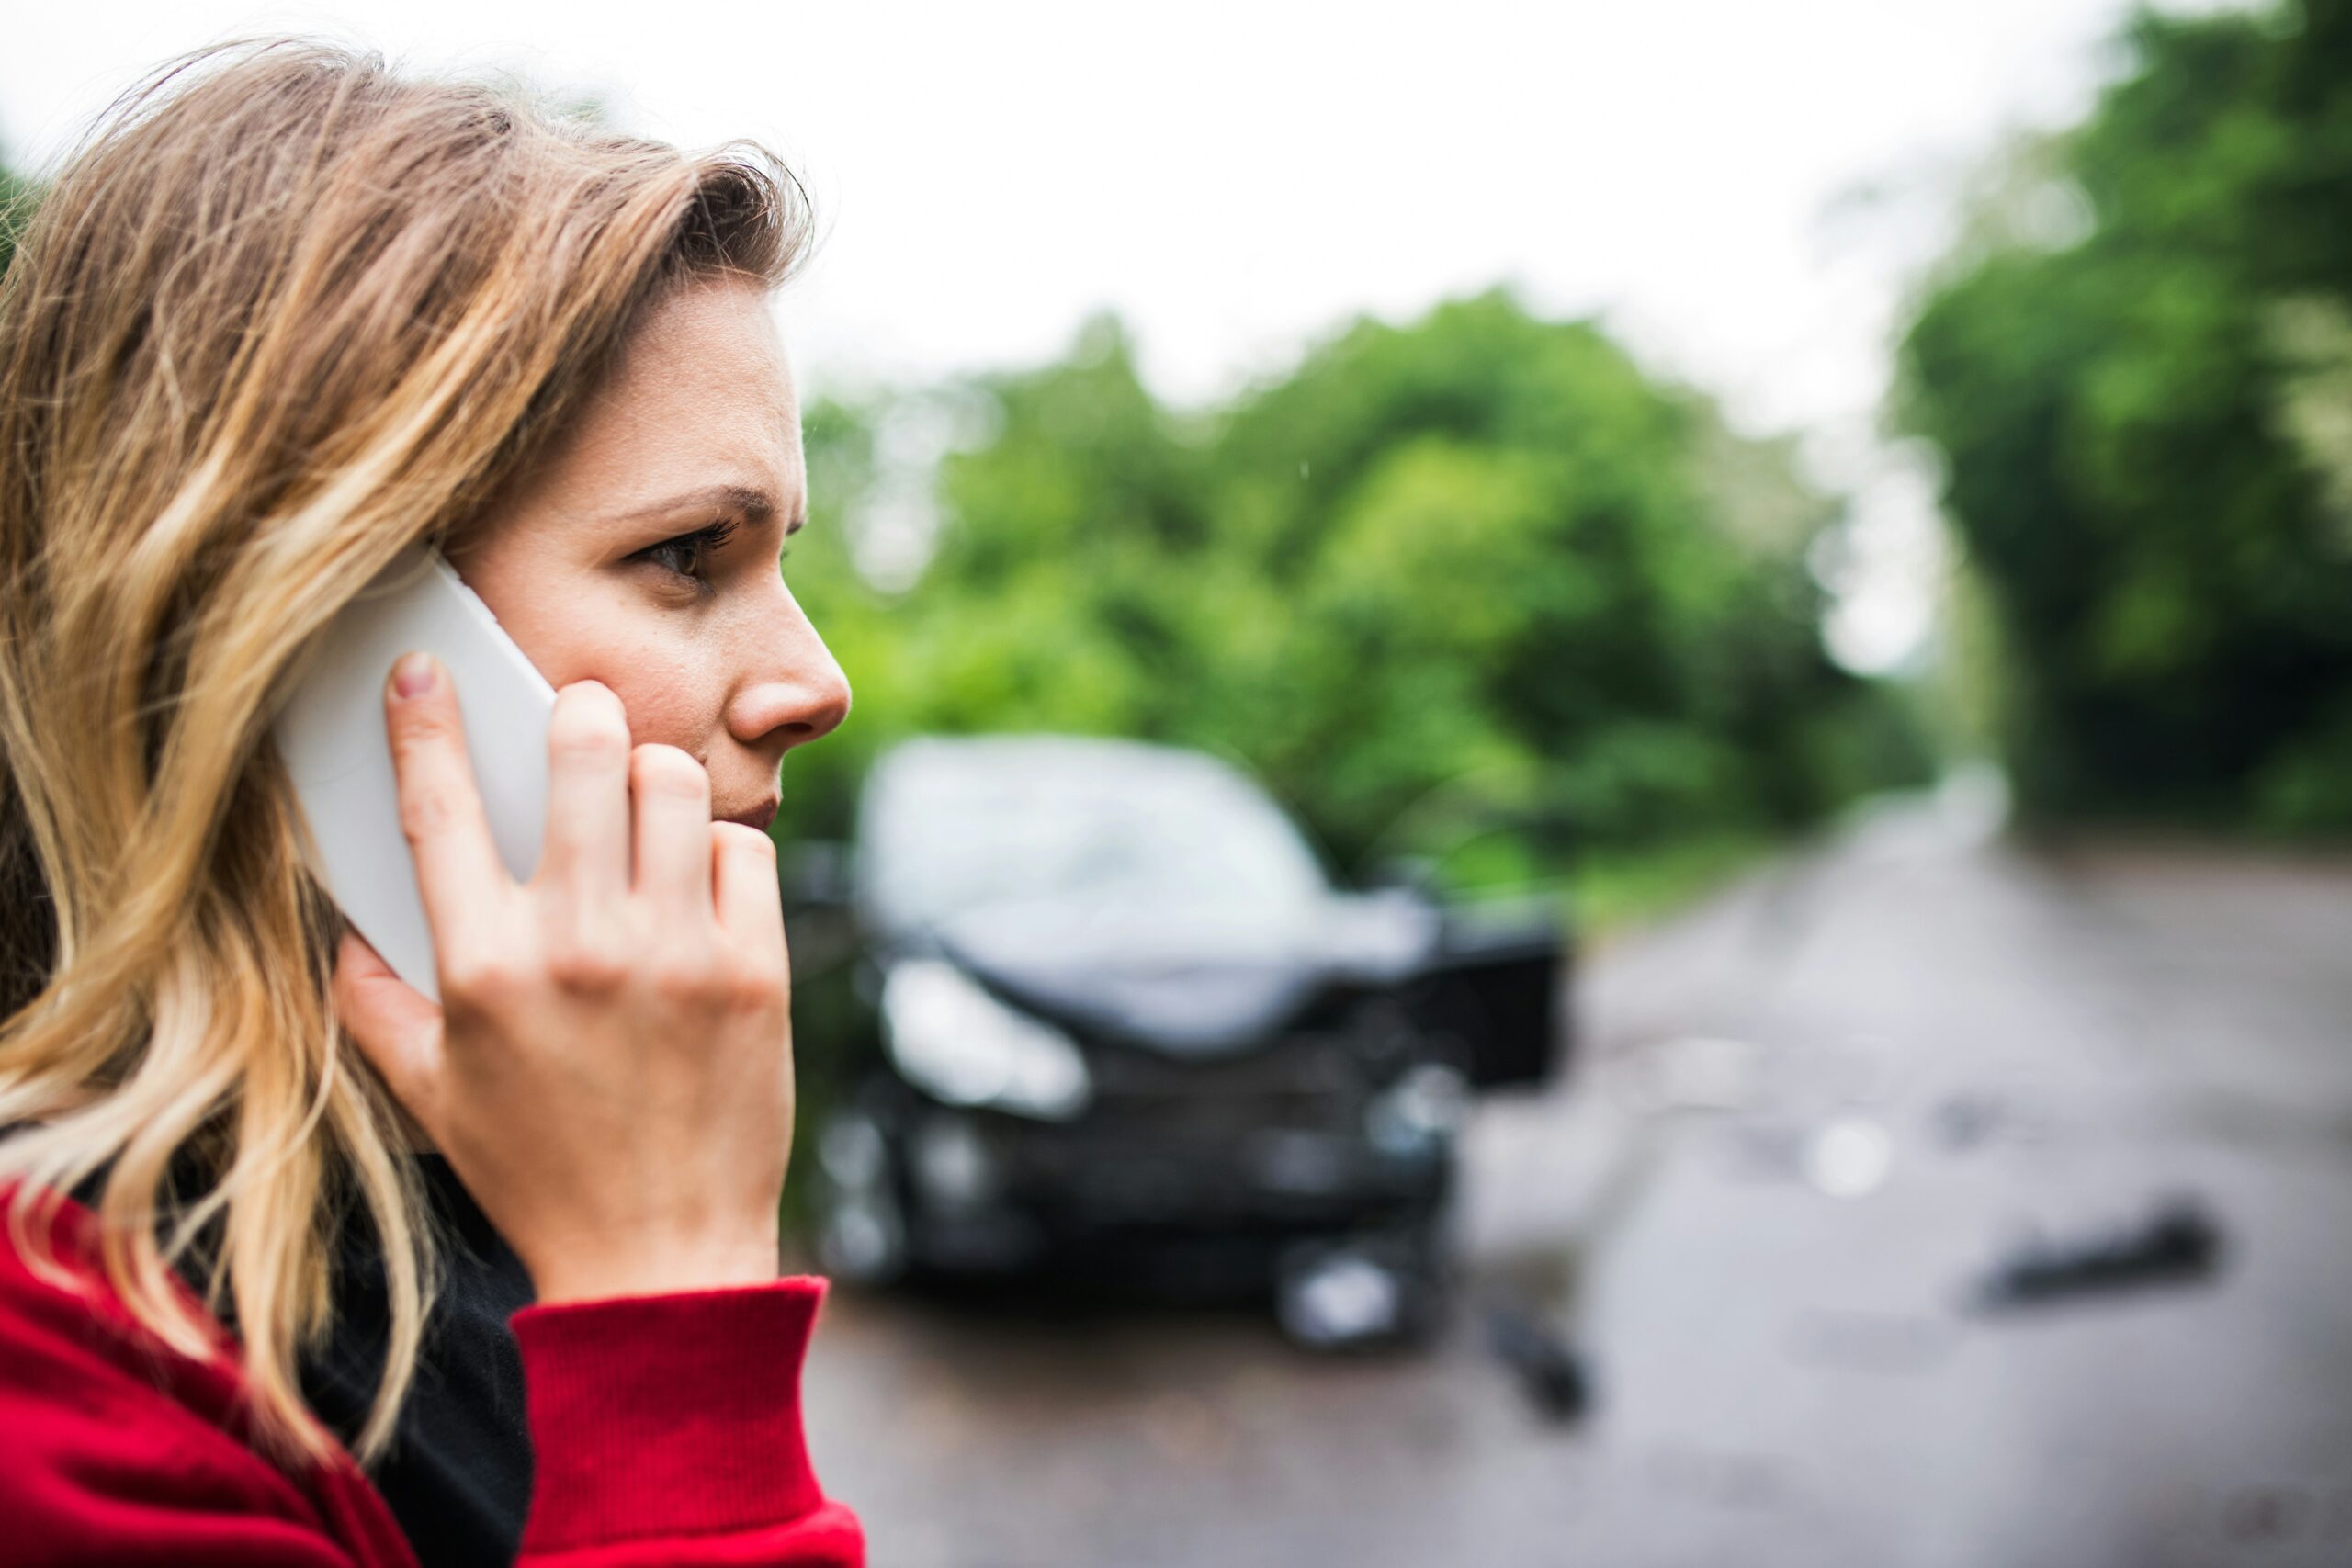
In the weeks after a collision, many people find that the hardest part is not the injury itself but the slow grind of dealing with the company that is supposed to pay for it. A large number of injured drivers put off speaking with an attorney because they assume the process is simple enough to manage alone, and by the time they realize the insurer has been quietly building a case against them, months of useful evidence have already slipped away.
Solid legal representation changes that balance, because someone who handles these claims daily can see what the adjuster is doing and why. Injured drivers and passengers often work with a car accident attorney in Tampa, FL for exactly that reason. The earlier that happens, the fewer openings the other side has to work with.
Why Delay Works So Well for an Insurance Company
Time is the cheapest tool an insurer has. Every week a claim sits unresolved is another week of bills arriving at your home, and the company knows that financial strain wears people down far more effectively than any argument about fault. A claim that might have been settled fairly in month two often settles for much less in month seven, simply because the person filing it has run out of patience and savings.
Delay also takes practical forms that are easy to miss. Requests for documents you already sent, a file that moves from one adjuster to another, a review that is always a few weeks from being complete. None of these look like refusals. Together they push the claim toward the point where accepting any offer feels like relief.
Arguing About Who Caused the Collision
Fault is the first place a claim gets attacked, because if responsibility can be shifted, the amount owed drops immediately. An insurer may argue that you braked too suddenly, that you were traveling faster than the conditions allowed, or that you had a chance to avoid the crash and did not take it. These arguments rarely need to be proven outright. They only need to create enough doubt to justify a smaller offer.
This is why what gets recorded at the scene matters so much. Photographs of vehicle positions, skid marks, road conditions, traffic signals, and visible damage are difficult to argue with later. Witness details are equally valuable and almost impossible to recover once everyone has driven away.
What an Undervalued Settlement Offer Looks Like
An offer that seems reasonable on the surface often covers only what is easy to count. Emergency treatment, a few follow-up visits, and repairs to the vehicle are simple to total up, so those are the numbers an early offer is built on. What it tends to leave out is everything that arrives later: ongoing therapy, specialist visits, procedures that become necessary once swelling subsides, and the income lost during months of recovery.
The personal cost of an injury is treated the same way. Pain, disrupted sleep, anxiety behind the wheel, and the inability to do things you used to do without thinking are real losses, but they do not come with a receipt. An insurer counting on a quick resolution has little reason to include them unless someone insists.
Gaps in Treatment and How They Are Used Against You
Few things weaken a claim faster than a stretch of weeks with no medical visits. Life gets in the way, appointments are expensive, and people frequently stop going once the worst of the pain passes. An adjuster reviewing that file sees something different: proof, in their view, that you had recovered and that anything you claim afterward belongs to some other cause.
Following the treatment plan through to its end protects the claim as much as it protects your health. If cost or scheduling makes that difficult, it is far better to raise the problem early than to leave an unexplained silence in the record.
When Blame Is Shared Between Drivers
Responsibility for a crash is not always assigned entirely to one person. Where both drivers are found to have contributed, the compensation available to the injured party is reduced in proportion to the share of blame placed on them. That creates a direct incentive for the other side to push as much responsibility onto you as it can, even when the main cause of the collision is obvious.
Countering that takes evidence rather than argument. Independent witness accounts, nearby camera footage, vehicle damage patterns, and the official report all help establish what actually happened, and each one becomes harder to obtain as time passes.
Protecting the Value of a Claim From Day One
Most of what determines the outcome of a claim is decided in the first few weeks, long before any serious negotiation begins. Getting examined promptly, keeping every bill and receipt, writing down how the injury affects your daily routine, staying off social media while the claim is open, and being careful about what you say to anyone representing the other driver all cost nothing and are nearly impossible to fix in hindsight.
Delay, dispute, and undervaluation are not obstacles that appear because something went wrong with your case. They are the standard approach, applied to almost everyone who files. Recognizing that early and preparing accordingly is what separates a claim that settles on the insurer's terms from one that settles on yours.